ME Group Albania | Ngjarjet ekonomike të javës | 28 tetor 2026
Paketa fiskale e propozuar për vitin 2027 prek TVSH-në, dividendin, pagat dhe procedurat tatimore. Ky material është përditësuar pas deklaratës së Kryeministrit Edi Rama të 28 tetorit 2026 dhe dallon masat e njoftuara publikisht nga nismat pa parametra të plotë dhe pikat e draftit që nuk u trajtuan posaçërisht. Njoftimi publik nuk barazohet me miratimin përfundimtar apo hyrjen në fuqi të ligjit.
Normat dhe pragjet kryesore
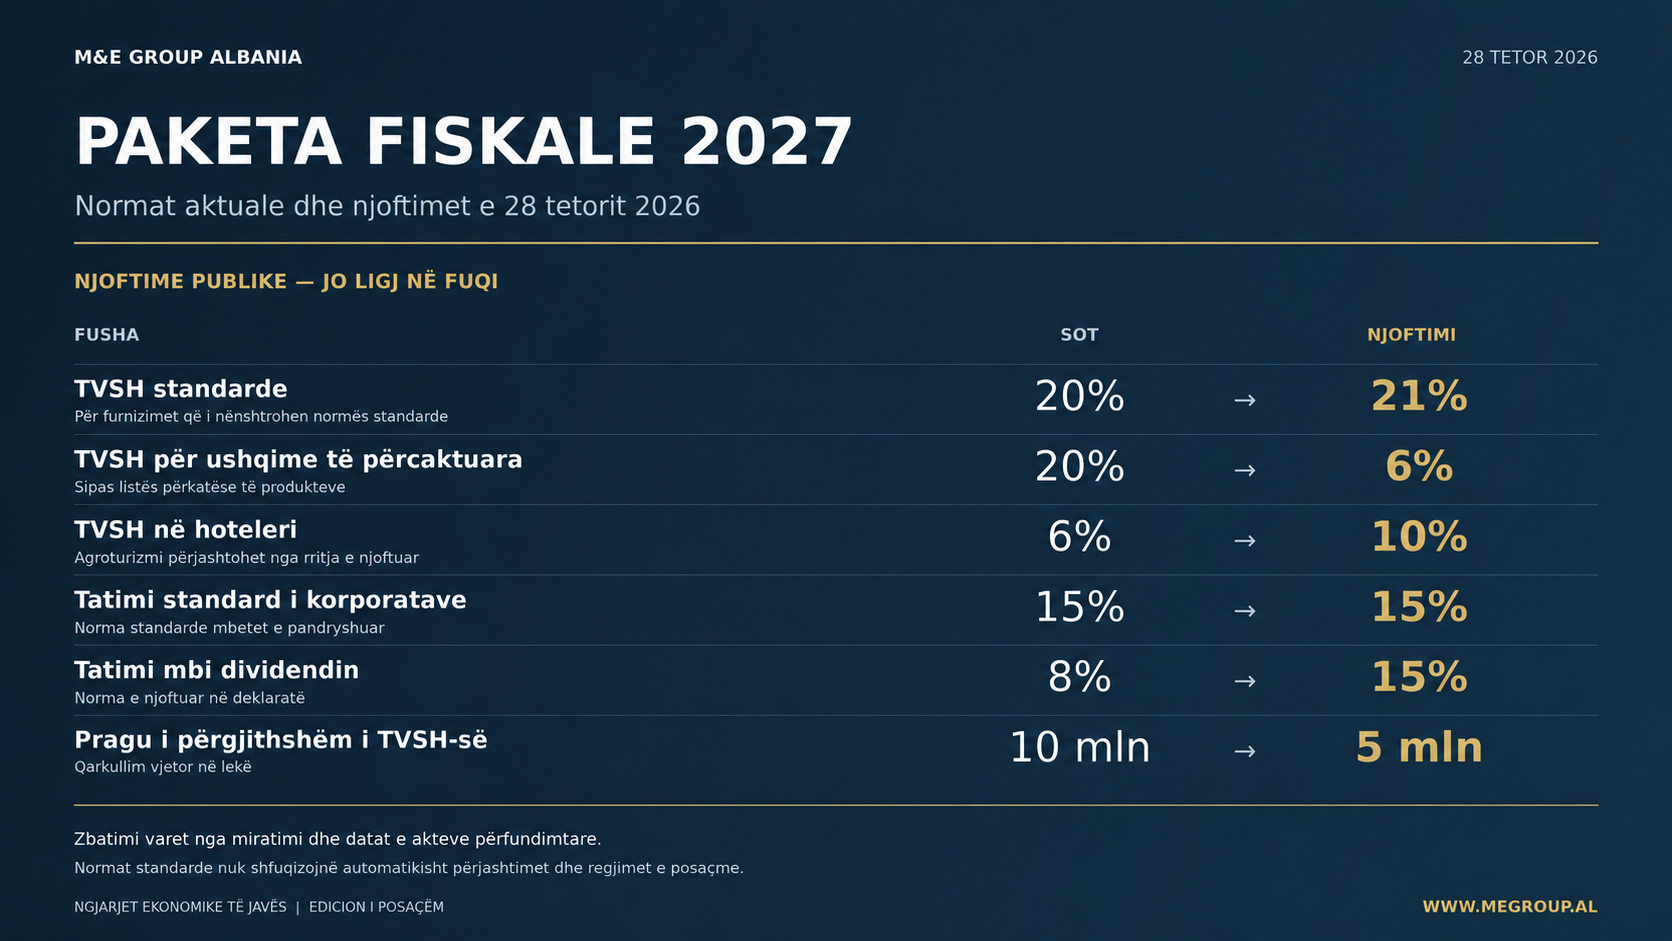
| Fusha | Si është | Njoftimi i 28 tetorit |
|---|---|---|
| TVSH standarde | 20% | 21% |
| TVSH për ushqime të përcaktuara | 20% | 6% sipas listës përkatëse |
| TVSH në hoteleri, përjashtuar agroturizmin | 6% | 10% |
| TVSH për agroturizmin e kualifikuar | 6% | Përjashtohet nga rritja e njoftuar në 10% |
| Pragu i përgjithshëm i regjistrimit në TVSH | 10 milionë lekë xhiro/vit | 5 milionë lekë xhiro/vit |
| Tatimi standard i korporatave | 15% | 15% — e pandryshuar |
| Tatimi mbi dividendin | 8% | 15% |
TVSH dhe biznesi i vogël
Në deklaratë u njoftua ulja e TVSH-së nga 20% në 6% për produktet bazë ushqimore dhe rritja e normës standarde në 21%. Lista përfundimtare e ushqimeve dhe kushtet e zbatimit duhen lexuar në aktet përkatëse. Rritja nga 6% në 10% u njoftua për hotelerinë, me përjashtim të agroturizmit; ajo nuk duhet paraqitur si rritje për çdo shërbim turistik.
Ulja e pragut të TVSH-së nga 10 në 5 milionë lekë xhiro vjetore prek kryesisht bizneset me xhiro 5–10 milionë lekë. U rikonfirmua angazhimi për tatim zero mbi fitimin e biznesit të vogël deri në vitin 2029, sipas kushteve ligjore. Norma 0% për subjektet e kualifikuara me të ardhura bruto deri në 14 milionë lekë mbetet e parashikuar deri më 31 dhjetor 2029. Regjistrimi në TVSH nuk sjell automatikisht humbjen e këtij trajtimi të tatimit mbi të ardhurat.
Fitimi dhe dividendi
Norma standarde e tatimfitimit mbetet 15%. Rritja e parashikuar në draftin e mëparshëm nuk paraqitet më si masa e njoftuar. Në deklaratë u njoftua rritja e tatimit mbi dividendin nga 8% në 15%. Për një shoqëri me 10 milionë lekë fitim të tatueshëm, tatim standard 15% dhe shpërndarje të plotë të fitimit pas tatimit te një individ, barra e kombinuar do të kalonte nga 2,18 në 2,775 milionë lekë, ose nga 21,80% në 27,75%, nëse ndryshimi i dividendit miratohet në këtë formë. Ky është një shembull llogaritës me supozimet e mësipërme; përjashtimet, normat e posaçme dhe marrëveshjet tatimore duhen kontrolluar sipas rastit. Normat 15% dhe 23% për fitimin e individëve tregtarë dhe të vetëpunësuarve nuk ndryshohen nga drafti i shqyrtuar.
Pagat dhe fashat progresive
Sot, pas zbritjeve personale, baza vjetore tatohet me 13% deri në 2,04 milionë lekë dhe 23% mbi këtë kufi. Në deklaratën e 28 tetorit, norma e njoftuar për pagat e larta ishte 30%, me referencë pagat bruto mbi 700 000 lekë në muaj. U njoftua gjithashtu rritja e pragut të fashës 23% nga 200 000 në 300 000 lekë pagë bruto mujore. Kufijtë vjetorë, zbritjet dhe formula progresive kërkojnë verifikim në tekstin e përditësuar; norma e sipërme nuk duhet aplikuar automatikisht mbi të gjithë pagën. Shembulli i draftit për një pagë bruto 500 000 lekë në muaj jep ulje të tatimit nga 91 100 në 81 100 lekë, vetëm nëse ruhen fashat, zbritja standarde 30 000 lekë/muaj dhe supozimet e tjera. Ai mbetet ilustrues deri në miratimin e formulës përfundimtare.
Masat e tjera të njoftuara nga Rama
Karburantet: u njoftua heqja e taksës së qarkullimit nga çmimi i naftës dhe zhvendosja e saj te automjeti, përmes një formule të re. Rama foli për ulje rreth 32 lekë/litër në pompë. Kjo është shifra e njoftuar prej tij; kostoja vjetore për drejtuesin nuk mund të llogaritet pa formulën e taksimit të mjetit.
Automjetet: u njoftuan taksim shtesë për makinat e luksit dhe një taksë e re qarkullimi për automjetet e huaja që hyjnë në Shqipëri. Nuk u dhanë normat, pragjet dhe përjashtimet përkatëse.
Prona: u njoftuan taksa shtesë për apartamentet që mbahen bosh dhe për vilat në bregdet, si dhe çmim i shumëfishuar për ujin e pishinave. Nuk u përcaktuan përqindje, pragje vlere apo kritere të hollësishme të zbatimit.
Ekonomia digjitale: u paralajmërua projekt i veçantë për taksimin e të ardhurave nga platformat online dhe tregtia digjitale. Nuk u shpall normë konkrete. Ky njoftim nuk do të thotë se këto të ardhura janë sot automatikisht të përjashtuara nga tatimi.
Kontrolli i të ardhurave: u njoftua krijimi i një byroje të specializuar për kontrollin e të ardhurave pranë Ministrisë së Financave dhe një formular më i detajuar për individët me të ardhura relativisht të larta. Nuk u shpall prag numerik për përfshirjen në formularin e ri.
Pikat e draftit pa konfirmim të posaçëm në deklaratë
Pikat për sponsorizimet, pasqyrat financiare, këstet tatimore, pagesat cash, kontrollet, dokumentacionin e transferimit të çmimit, përjashtimet personale, akcizat, biodieselin dhe regjimin e ALPEX ruajnë më poshtë statusin e propozimeve të draftit të shqyrtuar. Ato nuk paraqiten si të konfirmuara posaçërisht në deklaratë apo si të tërhequra. Mospërmendja në një deklaratë nuk ndryshon vetvetiu projektaktin; statusi i secilës pikë kërkon tekstin e përditësuar dhe vendimmarrjen përkatëse.
Sponsorizimet dhe përjashtimet personale — propozime të draftit
Për artin, sportin dhe kulturën, kufiri bazë i shpenzimit të zbritshëm propozohet të kalojë nga 5% e fitimit para tatimit në 3% të të ardhurave totale bruto. Vendosen tavane 300 milionë lekë për sponsorizues dhe 2 miliardë lekë në rang kombëtar, me vërtetim dhe autorizim paraprak. Shpenzimi nuk mbartet në vitet pasuese. Skema e posaçme sportive e zbritjes së trefishuar nuk ruhet në formulimin e ri.
Për shtypin, botimet dhe kërkim-zhvillimin ruhet kufiri 5% i fitimit para tatimit; për sponsorizime të tjera, 3%. Propozohet heqja e përjashtimeve për të ardhurat nga sponsorizimet te përfituesi dhe përjashtim personal për kategori të përcaktuara individësh e të vetëpunësuarish të vetëm me status të dokumentuar të aftësisë së kufizuar.
Pasqyrat financiare dhe administrimi tatimor — propozime të draftit
Pasqyrat financiare: synohet depozitimi në QKB dhe përcjellja elektronike te Tatimet, duke shmangur dorëzimin e dyfishtë. Versioni i publikuar ruan dorëzimin edhe në Tatime për pasqyrat e vitit 2026. Deklarata vjetore tatimore mbetet detyrim i veçantë.
Këstet e tatimit: propozohet trajtimi i parapagimeve të maturuara e të papaguara si detyrim tatimor që mund të ndiqet me mbledhje me forcë. Gjoba ekzistuese 0,06% në ditë, deri në 365 ditë, nuk rritet nga kjo ndërhyrje.
Pagesat cash: gjoba 10% e vlerës së transaksionit propozohet të shtrihet edhe te shkeljet biznes–individ. Kufijtë aktualë janë 100 000 lekë ndërmjet bizneseve dhe 500 000 lekë biznes–individ; këta kufij nuk janë risi e vitit 2027.
Kontrollet dhe dokumentacioni: gjatë çregjistrimit propozohet moszbatimi i afatit të zakonshëm të njoftimit për kontrollin mbi bazë risku, brenda kufirit 30 ditë pune. Për vonesën e dokumentacionit të transferimit të çmimit, që kërkohet nga Tatimet brenda afatit 45-ditor, propozohet gjobë 100 000–150 000 lekë.
Akcizat dhe energjia — propozime të draftit
Propozohet kalendar i ri akcizash 2027–2033 për duhanin dhe produktet alternative. Për cigaret, norma kalon nga 7 750 në 8 100 lekë për 1 000 fije në 2027; nga 2030 shtohet edhe komponent mbi çmimin e shitjes me pakicë. Ndryshojnë edhe normat për lëngjet me nikotinë, duhanin me ngrohje dhe kategori të tjera. Për biodieselin me vajra nafte raportohet kalimi nga 38,8 lekë/kg në 39,3 lekë/litër, ndaj krahasimi kërkon kujdes për njësinë.
Regjimi i posaçëm i TVSH-së për Bursën Shqiptare të Energjisë, që sot përfundon më 31 dhjetor 2026, propozohet të vijojë deri në anëtarësimin në BE.
Çfarë duhet të përgatisë biznesi
Rishikoni klasifikimin e artikujve, çmimet, kontratat me TVSH, listëpagesat dhe likuiditetin për këstet tatimore. Ndani ndikimin sipas regjimit të subjektit dhe klientelës. Ndryshimi i TVSH-së nuk përkthehet automatikisht në të njëjtën përqindje ndryshimi të çmimit final.
Për TVSH-në, tatimin mbi të ardhurat dhe pragun raportohet synimi 1 janar 2027. Për ndryshimet procedurale, data duhet lexuar veçmas në aktin përfundimtar. Mos aktivizoni normat e propozuara përpara hyrjes së tyre ligjore në zbatim.
Ky material ka karakter informues dhe nuk përbën këshillim ligjor, tatimor apo financiar. Burimet dhe lidhjet ruhen në dokumentin shoqërues të publikimit.
Burimi për deklaratën e 28 tetorit 2026: raportimi dhe transkriptimi nga TPZ. Njoftimet publike nuk zëvendësojnë aktet e miratuara dhe botimin në Fletoren Zyrtare.
ENGLISH VERSION
Albania’s 2027 Fiscal Package
The proposed fiscal package for 2027 covers VAT, dividends, salaries and tax procedures. This article has been updated following Prime Minister Edi Rama’s statement of 28 October 2026. It distinguishes publicly announced measures from initiatives without full parameters and draft provisions that were not specifically addressed. A public announcement does not amount to final legislative approval or entry into force.
Key rates and thresholds
| Area | Current rules | 28 October announcement |
|---|---|---|
| Standard VAT rate | 20% | 21% |
| VAT on specified food products | 20% | 6%, according to the applicable list |
| Hotel VAT, excluding agritourism | 6% | 10% |
| VAT for qualifying agritourism | 6% | Excluded from the announced increase to 10% |
| General VAT registration threshold | ALL 10 million in annual turnover | ALL 5 million in annual turnover |
| Standard corporate income tax rate | 15% | 15% — unchanged |
| Dividend tax | 8% | 15% |
VAT and small businesses
The statement announced a reduction in VAT from 20% to 6% for basic food products and an increase in the standard rate to 21%. The final food list and conditions must be checked against the relevant legislation. The increase from 6% to 10% was announced for hotels, excluding agritourism; it should not be described as an increase for every tourism service.
The reduction in the VAT registration threshold from ALL 10 million to ALL 5 million in annual turnover mainly affects businesses with turnover of ALL 5–10 million. The commitment to zero profit tax for small businesses through 2029 was reaffirmed, subject to the legal conditions. The 0% rate for qualifying taxpayers with gross income of up to ALL 14 million remains provided for until 31 December 2029. VAT registration does not automatically remove this income tax treatment.
Profits and dividends
The standard corporate income tax rate remains 15%. The increase in the earlier draft is no longer presented as the announced measure. The statement announced an increase in dividend tax from 8% to 15%. For a company with ALL 10 million in taxable profit, a standard corporate tax rate of 15% and full distribution of after-tax profit to an individual, the combined tax would rise from ALL 2.18 million to ALL 2.775 million, or from 21.80% to 27.75%, if the dividend change is enacted in this form. This is an illustrative calculation using those assumptions; exemptions, special rates and tax treaties must be checked individually. The 15% and 23% rates on the profits of individual traders and self-employed persons are not changed by the draft reviewed.
Salaries and progressive tax brackets
Currently, after personal deductions, the annual taxable base is taxed at 13% up to ALL 2.04 million and 23% above that threshold. In the 28 October statement, the announced rate for high salaries was 30%, referring to gross monthly salaries above ALL 700,000. An increase in the gross monthly salary threshold for the 23% bracket from ALL 200,000 to ALL 300,000 was also announced. Annual thresholds, deductions and the progressive formula must be verified in the updated text; the top rate should not automatically be applied to the entire salary. The draft example for a gross monthly salary of ALL 500,000 produces a tax reduction from ALL 91,100 to ALL 81,100 only if the brackets, the standard ALL 30,000 monthly deduction and the other assumptions remain unchanged. It remains illustrative until the final formula is approved.
Other measures announced by Rama
Fuel: the announcement envisages removing the circulation tax from the price of diesel and shifting it to vehicles through a new formula. Rama referred to a reduction of around ALL 32 per litre at the pump. This is the figure he announced; the annual cost for a driver cannot be calculated without the vehicle taxation formula.
Vehicles: additional taxation of luxury cars and a new circulation tax for foreign vehicles entering Albania were announced. The relevant rates, thresholds and exemptions were not specified.
Property: additional taxes were announced for apartments kept vacant and coastal villas, together with a substantially higher charge for swimming-pool water. Percentages, value thresholds and detailed implementation criteria were not specified.
The digital economy: a separate initiative was announced for taxing income from online platforms and digital commerce. No specific rate was announced. This does not mean such income is currently automatically exempt from tax.
Income oversight: a specialised income oversight bureau within the Ministry of Finance and a more detailed form for individuals with relatively high incomes were announced. No numerical threshold for inclusion in the new form was specified.
Draft provisions not specifically confirmed in the statement
The provisions on sponsorships, financial statements, tax instalments, cash payments, audits, transfer pricing documentation, personal exemptions, excise duties, biodiesel and the ALPEX regime retain their status below as proposals in the draft reviewed. They are not presented as specifically confirmed by the statement or as withdrawn. Omission from a public statement does not itself amend a draft; each provision must be checked against the updated text and the relevant decisions.
Sponsorships and personal exemptions — draft proposals
For arts, sports and culture, the basic limit for deductible expenditure is proposed to change from 5% of pre-tax profit to 3% of total gross income. Caps of ALL 300 million per sponsor and ALL 2 billion nationwide are introduced, subject to certification and prior authorisation. The expenditure cannot be carried forward to subsequent years. The special sports scheme allowing a triple deduction is not retained in the new wording.
For the press, publishing and research and development, the limit of 5% of pre-tax profit is retained; for other sponsorships, the limit remains 3%. The proposals also include removing exemptions for sponsorship income received by beneficiaries and introducing a personal exemption for specified categories of individuals and self-employed persons working alone who have documented disability status.
Financial statements and tax administration — draft proposals
Financial statements: the aim is to file them with the National Business Centre (QKB) and transmit them electronically to the tax authorities, avoiding duplicate submissions. The published version retains the requirement to submit the 2026 financial statements to the tax authorities as well. The annual tax return remains a separate obligation.
Tax instalments: the proposal treats overdue, unpaid advance payments as tax liabilities that may be subject to enforced collection. The existing penalty of 0.06% per day, for up to 365 days, is not increased by this amendment.
Cash payments: the penalty of 10% of the transaction value is proposed to extend to breaches involving business-to-individual transactions. The current limits are ALL 100,000 between businesses and ALL 500,000 for business-to-individual transactions; these limits are not new measures for 2027.
Audits and documentation: during deregistration, the proposal would disapply the standard advance-notice period for a risk-based audit, within the 30-working-day limit. A penalty of ALL 100,000–150,000 is proposed for late submission of transfer pricing documentation requested by the tax authorities within the 45-day deadline.
Excise duties and energy — draft proposals
A new excise duty schedule for 2027–2033 is proposed for tobacco and alternative products. For cigarettes, the rate rises from ALL 7,750 to ALL 8,100 per 1,000 cigarettes in 2027; from 2030, a component based on the retail selling price is also added. Rates also change for nicotine liquids, heated tobacco and other categories. For biodiesel containing petroleum oils, a change from ALL 38.8/kg to ALL 39.3/litre is reported, so comparisons require attention to the different units.
The special VAT regime for the Albanian Power Exchange, which currently expires on 31 December 2026, is proposed to continue until EU accession.
What businesses should prepare
Review product classifications, prices, contracts involving VAT, payroll and cash flow for tax instalments. Assess the impact according to the taxpayer’s regime and customer base. A change in VAT does not automatically translate into an equivalent percentage change in the final price.
For VAT, income tax and the registration threshold, the reported target date is 1 January 2027. For procedural changes, the effective date must be checked separately in the final legislation. Do not apply the proposed rates before they legally take effect.
This material is for information purposes only and does not constitute legal, tax or financial advice. Sources and links are retained in the document accompanying this publication.
Source for the 28 October 2026 statement: TPZ report and transcript. Public announcements do not replace enacted legislation and publication in the Official Gazette.